Clayton Glass Limited Falls Into Administration; Four of Seven Sites Saved in Pre-Pack Deal
Written by:
Published on:
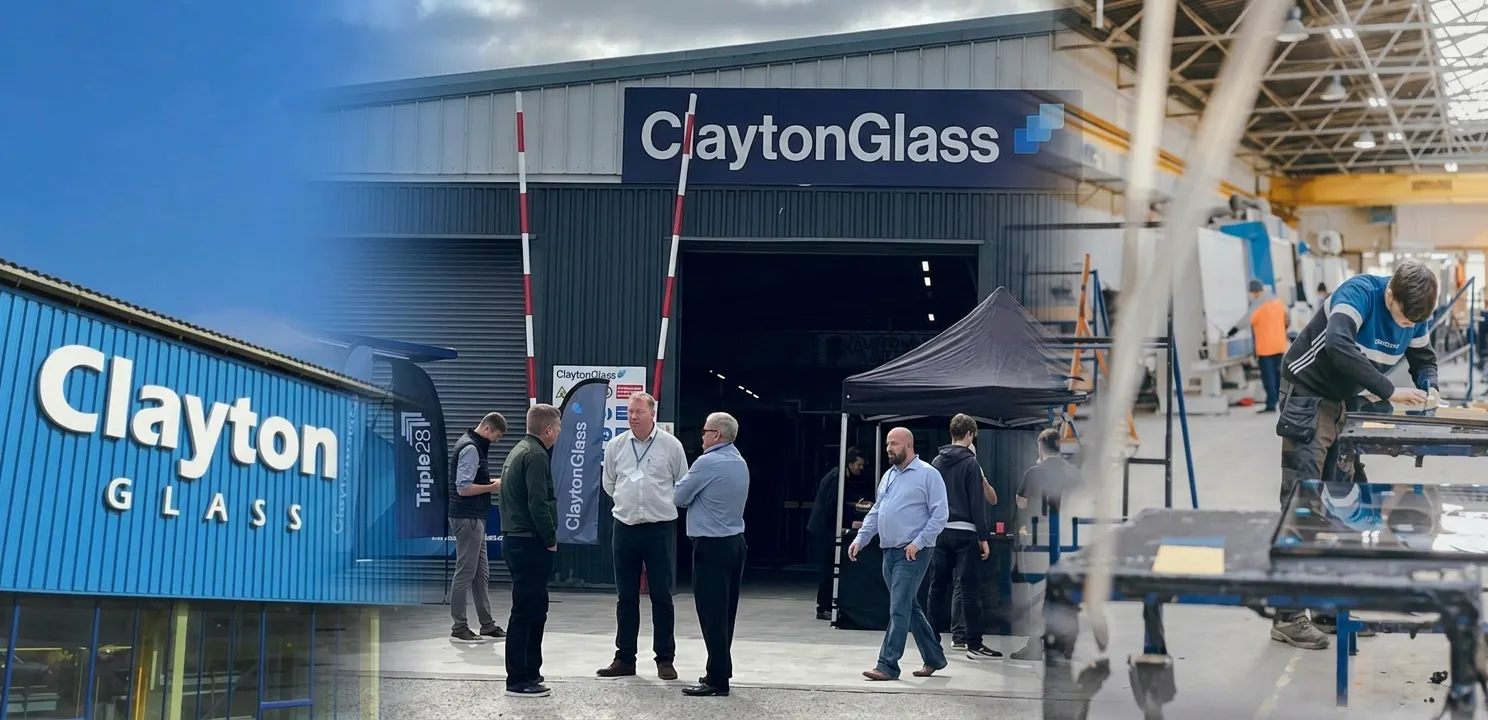
Clayton Glass Limited, a long-established IGU manufacturer supplying the window, door and conservatory trade, has been placed into administration and sold via pre-pack to a management-backed successor company, with four of its seven sites retained and the rest earmarked for closure.
Clayton Glass Limited (company number 05322333, incorporated 30 December 2004, previously registered as Broomco (3668) Limited) as an active company under SIC code 23120, covering the manufacture of glass. According to the administrator's reporting, the company manufactured and supplied insulated glass units to window, door, conservatory and glazing contractors from seven UK sites. Accounts covering the period 1 July 2024 to 31 March 2025 show fixed assets of approximately £7.1 million, current assets of £20.5 million and net assets of £3.3 million, with turnover of around £49.1 million for that nine-month period, down from £100.4 million in the prior eighteen-month period (1 January 2023 to 30 June 2024). Operating profit over the more recent period rose to £2.5 million from £1.3 million. Prior to the appointment, the company employed 573 staff across its site network. Further detail on trading history, customer contracts and specific site operations should be sought directly from the administrators at Interpath Advisory.
Find out more about the process of a company going into administration here.
Administration is a formal insolvency process that places an independent administrator in control of a company to protect it from creditor action while a rescue, sale or orderly wind-down is pursued. Here, Interpath Advisory was appointed and immediately executed a pre-pack sale an arrangement negotiated before or at the point of appointment and completed shortly after, transferring the business and certain assets to a new entity, Clayton Glass Group Limited, backed by the former management team. The Nottingham, Swindon, Canterbury and Dewsbury sites transferred as part of the deal, securing more than 280 jobs, while 290 staff were made redundant and the remaining sites will close. For buyers, the practical position is that the going-concern trading operation has already changed hands; what may still be available are the assets, plant, leases or freeholds tied to the sites and headcount that were not retained. Interested parties should approach Interpath Advisory directly to establish what, if anything, remains unsold from the closed locations.
The company's stated causes were high and rising energy costs, elevated raw material prices, and an extended period of low demand across the housing supply market, which together left it unable to maintain margins or meet its financial obligations. Glass and glazing manufacturers sit deep in the housing supply chain, making them sensitive to the same cost and demand cycles affecting new-build and home-improvement activity energy-intensive processing, imported material inputs, and demand that tracks mortgage rates and consumer confidence. Interpath's own comment that the industry is seeing 'a similar story across a range of businesses supplying the housing market' points toward sector-wide margin compression rather than a company-specific operational failure, though no other named businesses are confirmed in this dataset. The turnover fall from £100.4 million across an eighteen-month period to £49.1 million across nine months is consistent with this demand slowdown, though the unequal reporting periods mean the headline figures should be normalised before drawing firm conclusions. Net assets of £3.3 million against current assets of £20.5 million point to a thin equity buffer relative to working-capital exposure at the point of filing.
The going-concern core of the business the Nottingham, Swindon, Canterbury and Dewsbury sites and over 280 roles has already transferred via pre-pack, so this is not an open acquisition opportunity for that part of the group. The residual opportunity, if any, lies in the sites among the original seven that are closing, along with associated fixed assets valued at approximately £7.1 million pre-administration, which may include IGU manufacturing plant, equipment and site leases or freeholds not retained by the successor company. Buyers should note that pre-pack sales to connected parties here, a vehicle backed by former management typically attract SIP16 scrutiny, meaning administrators will generally have tested achievable value carefully before completion, which may limit negotiating room on any remaining assets. The 290 redundancies also carry potential TUPE and employment liability considerations for anyone acquiring specific closed-site premises or equipment, and these should be diligenced separately from the pre-pack transaction itself.
No. The trading business and its core sites Nottingham, Swindon, Canterbury and Dewsbury have already been sold via pre-pack administration to Clayton Glass Group Limited, a company backed by the former management team. Any remaining opportunity would relate to assets tied to the sites that were not retained, and interested parties should contact Interpath Advisory to confirm availability.
Reported figures show operating profit increased from £1.3 million to £2.5 million even as turnover nearly halved, which may indicate cost-cutting or repricing was already underway ahead of the filing. The company cited high and rising energy and raw material costs and soft housing-market demand as the drivers, alongside a thin net asset position of £3.3 million relative to £20.5 million of current assets suggesting the failure was rooted in balance-sheet and cash pressure rather than an inability to generate profit on remaining volumes.
Interpath Advisory's administrator commentary described a 'similar story across a range of businesses supplying the housing market', framing high fixed costs and soft demand as sector-wide pressures rather than issues unique to Clayton Glass. For acquisition professionals, this points to a market where distressed but structurally viable operations may keep surfacing, with pre-pack sales retaining a core footprint while surplus capacity is shed a pattern worth watching for similarly structured targets.
For buyers researching similar opportunities, Administration List’s insolvency search pages can also help identify distressed transport and logistics businesses entering formal insolvency procedures across the UK.