Bodycare Enters Administration After Failed IPO Leaves Debt-Funded Expansion Unsupported
Written by:
Published on:
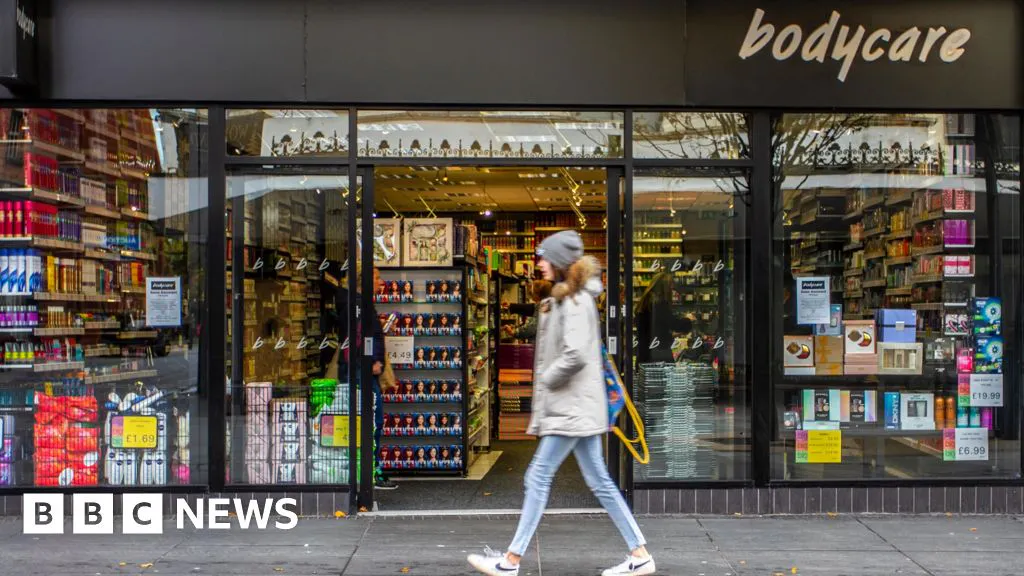
Bodycare, a UK health and beauty retailer trading since 1970, collapsed into administration on 5 September 2025 after a debt-funded post-takeover expansion and an abandoned 2024 IPO left it unable to bridge a funding gap, resulting in the closure of nearly 150 stores and around 1,400 job losses.
Bodycare was founded in 1970 and built a 55-year trading presence on UK high streets, latterly operating from a Lancashire base with nearly 150 stores nationwide at the time of its collapse. The business was acquired in 2020 by JDS52, an entity controlled by investor Jaswinder Singh, after which it pursued an ambitious expansion strategy involving new stores, a push into southern England and the launch of own-brand product lines. According to reported facts, the trading entity relied on financial support from parent company G.R. & M.M. Blackledge plc, as disclosed in subsidiary accounts, while a related dormant subsidiary, Bodycare (Health & Beauty) Limited, carried net liabilities of £8.29 million at the end of both 2022 and 2023. Companies House records confirm a group entity, Bodycare Group Limited (company number 16136736), incorporated on 16 December 2024 and now dissolved consistent with corporate restructuring undertaken around the time of the aborted IPO. Detailed trading accounts for the core operating business are not covered by the facts available here; advisers or the appointed administrators would be the primary source for a full financial picture.
Find out more about the process of a company going into administration here.
Administration is a formal insolvency process in which an appointed administrator takes control of a company to try to rescue it, achieve a better outcome for creditors than liquidation, or realise assets for distribution. Bodycare entered administration on 5 September 2025 after advisers brought in during summer 2025 had explored rescue options and secured a £7 million debt facility. That facility bought time rather than resolving the underlying funding gap, and within weeks administrators announced the closure of all remaining stores an outcome consistent with a managed wind-down rather than a pre-pack sale to a new owner. For buyers, this means the trading business itself is not available as a going concern; any acquisition opportunity now lies in discrete assets brand, stock, own-brand product lines, leases or fixtures that administrators may still be realising. Parties interested in these residual assets should approach the appointed administrators directly, since the facts available do not name the office-holder.
The reported drivers of Bodycare's collapse combine sector-wide pressure with company-specific decisions. Value-led health and beauty retailers on the high street have generally faced intensifying competition from online retailers and larger chains, compounded by a cost-of-living squeeze on price-sensitive shoppers and structurally rising rents and wage bills pressures Bodycare experienced directly, according to reported facts, alongside a failure to modernise its online offering. These sector headwinds were sharpened by company-specific strategy: the post-2020 expansion into new stores and southern England, together with an own-brand launch, added cost and complexity without a corresponding uplift in trading resilience. When the planned 2024 IPO was abandoned, an anticipated equity injection failed to materialise, leaving a funding gap that the subsequent £7 million debt facility could not close. Total debts exceeding £30 million against an estimated £34.9 million total deficiency to creditors indicate the business was materially insolvent by the time of appointment, and supplier concern over its financial position triggered stock shortages that further undermined trading in the run-up to collapse. Discounted sales of major third-party brands, including L'Oréal, Nivea, Elizabeth Arden and Lynx, in the final period are consistent with a distress liquidation of stock rather than ordinary promotional activity.
For acquisition professionals, the case offers several practical signals. First, the absence of a going-concern sale full closure followed the initial 32-store cull within weeks confirms no buyer emerged for the business as a whole, so opportunities will be piecemeal rather than a single transaction. Second, residual value is more likely to sit in the Bodycare brand name and its 55-year high-street heritage, plus the own-brand ranges developed during the 2020 - 2024 expansion, than in the store estate itself, which was being vacated. Third, individual leases in locations acquired during the southern England push, or at the Lancashire base, may be attractive to other value retailers looking to backfill space without taking on Bodycare's legacy liabilities. Finally, the scale of the deficiency with HMRC owed around £3 million as a preferential creditor and unsecured creditors facing losses of roughly £29.8 million means buyers of any residual assets should expect a clean-break purchase from the administrator rather than a negotiated exit with existing creditors.
No. Administrators closed an initial 32 stores with around 450 redundancies shortly after the 5 September 2025 appointment, then wound down the remaining stores within weeks, taking total job losses to around 1,400. This was a full closure rather than a rescue or pre-pack sale, so the business is not available as a going concern.
Based on the reported facts, likely residual assets include the Bodycare brand and its 55-year trading heritage, own-brand product lines developed during the 2020 - 2024 expansion, remaining stock, and individual store leases in the Lancashire heartland and southern England sites acquired during the expansion. Interested parties should contact the appointed administrators for specifics, as they are not named in the available facts.
The case illustrates the risk of funding store expansion and own-brand development with debt while awaiting an equity event such as an IPO. When that event failed to complete, Bodycare had no fallback beyond a stopgap debt facility, against a backdrop of online competition, rising rents and wage costs, and cost-of-living pressure on discretionary spending conditions common across the value retail sector that make similarly leveraged expansion strategies worth scrutinising by prospective acquirers and lenders alike.
For buyers researching similar opportunities, Administration List’s insolvency search pages can also help identify distressed transport and logistics businesses entering formal insolvency procedures across the UK.